

Simplifying VAT Return Filing in the UAE (including changes in 2026 and how to prepare)
VAT has been part of doing business in the UAE since January 1, 2018, and…
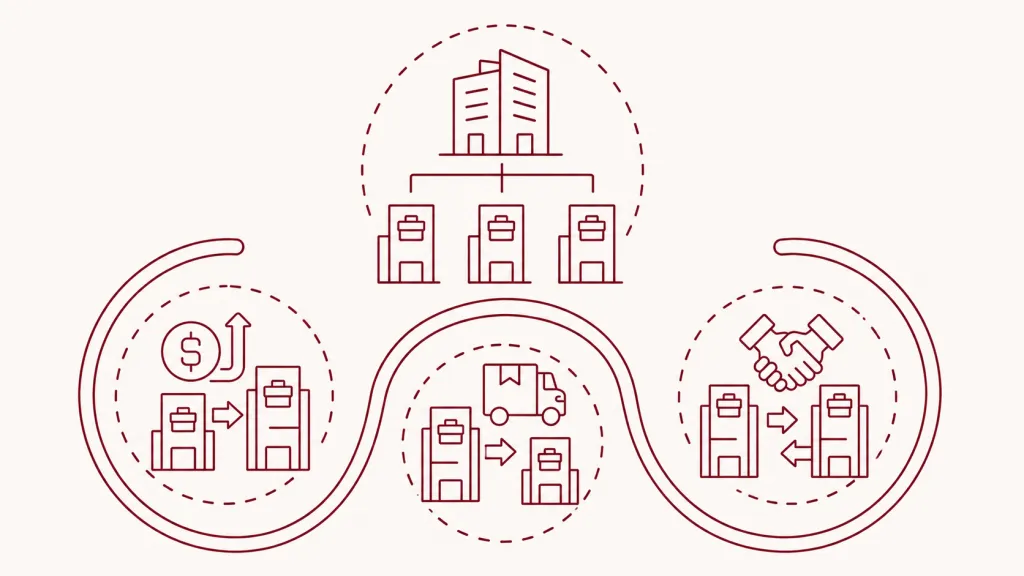
A UAE Tax Group is treated as a single Taxable Person for Corporate Tax purposes.
A UAE-resident parent company must directly or indirectly hold at least 95% of the share capital, voting rights, and entitlement to profits and net assets of the subsidiaries included in the Tax Group. The entities must also have the same financial year and use the same accounting standards.
The parent company and subsidiaries must also not be Exempt Persons or Qualifying Free Zone Persons.
Once a Tax Group is formed, the parent company is responsible for filing one Corporate Tax return and settling the group’s Corporate Tax liability.
To determine the Tax Group’s taxable income, the parent company consolidates the financial accounts of its subsidiaries and eliminates transactions between Tax Group members.
This treatment is different from transactions between a Tax Group member and a Related Party that is outside the Tax Group. UAE transfer pricing rules apply to domestic as well as cross-border transactions between Related Parties and Connected Persons.
The Federal Tax Authority (FTA) can adjust taxable income where the results of a Related Party transaction do not fall within the arm’s-length range. Failure to comply with transfer pricing regulations can lead to adjustments in taxable income by UAE authorities.
Note
A Qualifying Free Zone Person (QFZP) must comply with the arm’s length principle and maintain transfer pricing documentation as part of the conditions for QFZP status.
Bear in mind that a free zone entity benefiting from the Qualifying Free Zone Person regime cannot be a member of a UAE Tax Group.
Transactions between members of a Tax Group are no longer treated separately when the group’s financials are consolidated.
The Tax Group therefore does not calculate Corporate Tax as though each intra-group transaction were a transaction with an independent third party. The parent company consolidates the subsidiaries’ financial accounts to determine the Tax Group’s taxable income and eliminates transactions between the parent and its subsidiaries.
This means that ordinary intercompany transactions between Tax Group members, such as management charges or other internal dealings, do not increase the Tax Group’s taxable income.
Transactions between Tax Group members do not need to comply with transfer pricing rules, except where a member needs to calculate its standalone taxable income for specific purposes, such as using Tax Losses incurred before joining the Tax Group or when leaving the Tax Group.
When companies operate as part of a group, the tax law pays close attention to how transactions between related parties are priced. This is where the transfer pricing rules apply.
If a UAE Tax Group member transacts with a Related Party outside the Tax Group, the transaction remains within the UAE transfer pricing rules.
The UAE rules apply to both domestic and cross-border Controlled Transactions, including transactions between UAE entities and transactions involving Free Zone Persons.
Controlled Transactions include the supply or transfer of goods, provision or receipt of services, funding and other financial transactions, and transactions involving intangible assets such as patents, brands and know-how.
Therefore, a transaction with a foreign parent, UAE sister company outside the Tax Group, or another Related Party outside the Tax Group cannot be treated as eliminated merely because the entities belong to the same wider corporate group.
The transaction must generally satisfy the arm’s length principle.
The arm’s length principle requires Related Parties and Connected Persons to transact as if they were independent parties dealing under comparable circumstances.
The FTA describes a comparability analysis as a central part of applying the arm’s length principle.
The analysis compares the conditions of a Controlled Transaction with those that would have applied between independent parties in a comparable transaction.
Relevant factors include the contractual terms, characteristics of the transaction, economic circumstances, functions performed, assets used, risks assumed and business strategies.
The UAE Corporate Tax Law provides five transfer pricing methods, broadly aligned with the OECD Transfer Pricing Guidelines. If none can reasonably be applied, another method may be used if the taxpayer can demonstrate why.
Note
A Related Party disclosure schedule is required where the aggregate value of transactions with all Related Parties exceeds AED 40 million in the relevant Tax Period; once this threshold is exceeded, transactions exceeding AED 4 million per category are subject to disclosure.
Intra-group transactions between members of the same corporate tax group are generally ignored for tax purposes, considering that they are treated as one taxable person.
Intra-group transactions include shared corporate services and financial exchanges between related entities.
For financial-related instances, intra-group transactions can include loans between a parent and subsidiary, loans between subsidiaries, or financing arranged through a group’s treasury function.
For example, if Company A charges Company B for management services, there is generally no impact on taxable income at Tax Group level where both companies are members of the same UAE Tax Group and the transaction is eliminated on consolidation.
The FTA may examine whether transactions are correctly classified as intra-group, whether entities should have been grouped at all, or whether profits were shifted outside the UAE. Proper documentation supports compliance and protects the group if structure changes later.
The FTA can make a transfer pricing adjustment if the transaction is not reflective of Market Value or the arm’s length price.
The UAE Corporate Tax Law requires arm’s-length pricing for related party transactions. In other words, transactions outside the group follow a different principle when a member transacts with:
In practice, the arm’s length principle requires prices, fees, margins or interest rates to reflect market terms. This must be properly documented; transfer pricing documentation may still be required at group level.
Benchmarking may be required to confirm arm’s-length pricing in UAE.
For Corporate Tax purposes, a UAE Tax Group brings the financial results of its members together in consolidated financial statements.
This means intercompany balances between Tax Group members are removed when the accounts are consolidated, so they do not affect the group’s overall taxable income. The transactions themselves still remain in each company’s accounting records.
Even though intragroup transactions within a tax group are ignored for tax calculations, documentation is required when:
Documentation typically supports pricing methods used, comparability analysis to market rates, and commercial rationale for the transaction.
UAE Corporate Tax Law prescribes five transfer pricing methods, which may look at comparable prices, costs and mark-ups, or net profit margins.
Transfer pricing methods must align with OECD guidelines.
Net book value may also be relevant for certain asset or liability transfers qualifying for Qualifying Group Relief, but it is not a transfer pricing method.
Contemporaneous records of intercompany pricing must be kept for seven years according to UAE regulations. This aligns with general corporate tax compliance, wherein records must be kept for at least seven years following the end of the relevant tax period.
For a deeper look at the arm’s length principle, transfer pricing methods, and Related Party transactions, see our guide on Transfer Pricing in the UAE.
Note:
Transfer pricing for CT and VAT are separate areas of UAE tax compliance.
The VAT treatment depends on transactions between related or connected parties; key elements of VAT compliance require businesses to explain the nature of the transaction and the applicable VAT rules.
Businesses should therefore assess the VAT treatment separately, including the applicable rules on the supply, input VAT recovery and supporting records.
Master File and Local File requirements apply to a Taxable Person where either:
The Master File and Local File must be provided to the FTA within 30 days of a request. A Local File contains detailed information about specific Controlled Transactions, including financial information, the comparability analysis and the selected transfer pricing method.
Businesses should keep records that explain how Related Party transactions were priced and treated for Corporate Tax purposes.
For related-party services outside the Tax Group, the FTA guidance notes that the analysis should consider the value of the service to the recipient, what an independent enterprise would have been willing to pay, and the costs incurred by the service provider.
For related-party loans, factors such as the loan’s tenor, currency, interest-rate type, borrower creditworthiness and comparable third-party loans can be relevant to determining an arm’s-length price.
A Connected Person is different from a Related Party and includes certain persons connected to a Taxable Person, such as an owner, director or officer, as well as their Related Parties.
Transfer pricing documentation helps demonstrate how a Controlled Transaction was priced and how the taxpayer applied the arm’s length principle, which helps if the FTA reviews the transaction.
Under Federal Decree-Law No. 47 of 2022, the Tax Group rules treat eligible members as a single Taxable Person, but this treatment does not continue for a company once it leaves the group.
Thus, a company leaving a Tax Group may need to calculate its taxable income on a standalone basis for certain purposes, such as using Tax Losses incurred before it joined the group.
Once the companies are no longer members of the same Tax Group, transactions between them are no longer eliminated as Tax Group transactions and may be subject to the transfer pricing rules if the companies remain Related Parties.
The change in the entire group structure therefore matters, particularly where a legal entity leaves the Tax Group and transactions between the former members continue.
Tax Group treatment, Qualifying Group Relief, and Business Restructuring Relief are separate Corporate Tax mechanisms, each with different relief eligibility requirements. Specific relief is available for certain intra-group asset and liability transfers to ensure tax neutrality.
While Tax Group rules consolidate the taxable results of multiple entities into a single Taxable Person, Qualifying Group Relief can provide tax-neutral treatment for certain transfers of assets or liabilities between qualifying companies, generally at net book value.
Business Restructuring Relief, on the other hand, can apply to qualifying business transfers or transfers of an independent part of a business, subject to the conditions set out in the Corporate Tax Law.
Businesses should therefore look at the specific transaction, group structure, and applicable conditions rather than assuming that all intra-group transfers receive the same treatment under similar circumstances.
Maintaining the right records and meeting regulatory compliance requirements is important when relying on any of these mechanisms.
Note
A Tax Group may elect for Small Business Relief for Tax Periods ending on or before 31 December 2029, if the relevant conditions are met. The AED 3 million Revenue threshold applies to the Tax Group’s consolidated Revenue, rather than to each member individually.
Thank you!
We've received your request and will get back to you shortly.
Loading...
 Thank you!
We've received your request and will get back to you shortly.



 Contact Us


