

How To Assign Invoice Numbers Correctly in UAE?
Have you ever found yourself knee-deep in invoices trying to reconcile a supply with payments…
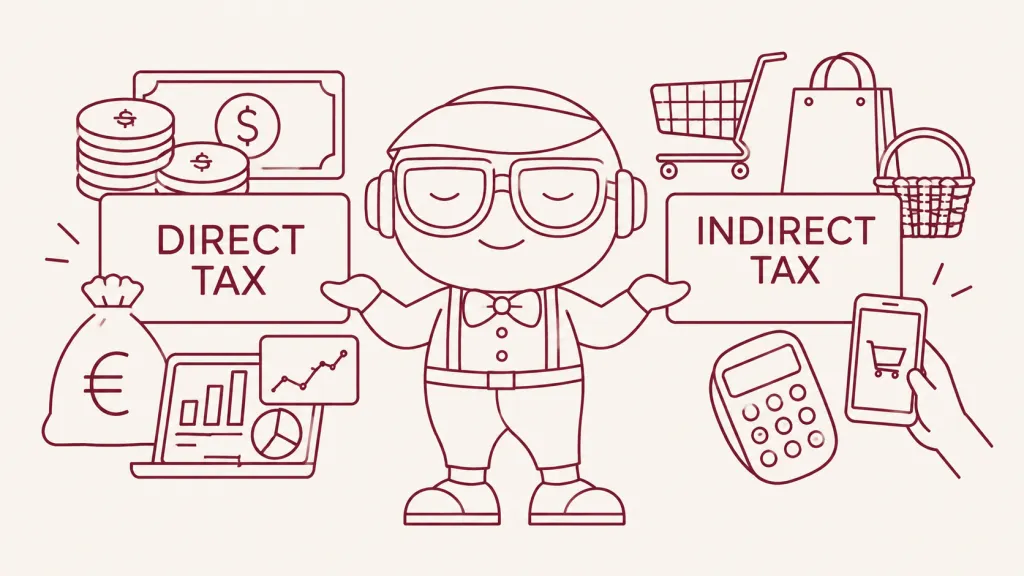
The UAE has both direct and indirect tax, but they work in very different ways.
Corporate Tax is a direct tax because it is imposed on a business’s taxable income, while VAT is an indirect tax because it is charged on taxable supplies and ultimately borne by the consumer.
The Federal Tax Authority (FTA) administers federal Corporate Tax, VAT and Excise Tax, including their registration, filing and payment requirements. Customs duties are administered separately under the UAE and GCC customs framework.
For UAE founders and finance teams, it helps to understand the nature of each tax system. The two types of tax have different tax bases, which has a direct impact on registration thresholds, reporting requirements and implications for cash flow. A business may also need to comply with both at the same time.
This guide explains how direct and indirect tax work in the UAE, covering Corporate Tax, VAT obligations, Excise Tax and customs duties, as well as the key registration and compliance requirements businesses need to understand.
Direct tax is a broad term used for taxes imposed directly on a person or entity based on income, profits, gains, property, or overall wealth, depending on the jurisdiction and particular tax.
The legal obligation to pay a direct tax falls directly on the taxpayer, rather than passing the tax on as part of the price of a transaction.
Direct taxes can be progressive, proportional, or regressive.
These are general classifications of how tax rates operate, but tax regulations in UAE have become more nuanced over the years.
For the UAE specifically, the key direct-tax example for businesses is Corporate Tax.
UAE Corporate Tax applies to taxable income, with:
Note that this refers to taxable income, and not the gross revenue.
Example:
Note
Calculating taxable income starts from accounting net profit/loss and is adjusted for items specified under the Corporate Tax Law.
Therefore, founders should not interpret “9% above AED 375,000” as a 9% tax on turnover or gross revenue.
Being established in a UAE Free Zone does not automatically mean 0% Corporate Tax.
A Qualifying Free Zone Person can benefit from:
Qualifying Free Zone Persons have specific conditions, including requirements relating to qualifying activities, excluded activities, substance and compliance.
Free Zone companies still have Corporate Tax registration and compliance obligations. You can check out Corporate tax filing guide for Qualifying Free Zone Persons here.
The UAE does not have a general personal income tax.
However, a natural person conducting a business or business activity in the UAE can fall within Corporate Tax.
The threshold is AED 1 million of annual business/business-activity turnover, not AED 375,000 of taxable income.
Certain income is excluded from the business-activity calculation, including:
In many countries, payroll taxes include personal income tax withheld from employees’ salaries, making them a form of direct taxation.
The UAE does not impose a general personal income tax on employees, so employers do not generally withhold UAE income tax from employee salaries.
However, employers may have other payroll-related statutory obligations, including pension and social security contributions for eligible UAE and GCC national employees.
These contributions should not be confused with Corporate Tax or personal income tax. They are employment-related statutory contributions rather than a general tax on salary income.
Employers must also account for employment obligations such as wages and end-of-service benefits, but these are likewise not classified as payroll taxes.
The UAE does not levy a general federal estate/inheritance tax comparable to estate taxes in some other jurisdictions.
There can be other fees, transfer charges and legal considerations around assets and inheritance.
The UAE does not have a separate standalone federal “capital gains tax” in the way some jurisdictions do.
However, capital gains can form part of taxable income under Corporate Tax.
The FTA states that gains from disposal of assets are generally included in annual taxable income in the same way as other business income. There are exemptions and reliefs in particular circumstances.
For example, qualifying capital gains from a Participating Interest may benefit from the participation exemption, subject to the relevant conditions.
In this guide, we outline participation exemption for dividends and capital gains.
Property tax is a common form of direct tax on real estate worldwide. However, the UAE itself does not impose a general annual property tax on residential real estate.
Property owners may instead face transfer, registration, municipality and service charges. Commercial real estate can also have VAT and Corporate Tax implications depending on the transaction and how the property is held.
One-Time Buying fees include:
For ongoing ownership costs on real properties:
For commercial properties:
Indirect taxes are taxes levied on transactions, supply, consumption, or specific goods/services. The tax is typically collected by an intermediary in the supply chain and accounted for to the government.
The UAE’s major federal indirect taxes are:
Customs duties are another cost associated with importing goods, but technically sit within the UAE/GCC customs framework rather than being interchangeable with VAT or Excise Tax.
With indirect taxes, the economic burden is typically passed to the consumer, while businesses may have the legal responsibility for collecting and remitting the tax. VAT is the clearest UAE example for this.
Consumption taxes can disproportionately affect lower-income consumers because they spend a larger share of income on consumption.
Indirect tax compliance is often simpler for consumers as it is embedded in prices. Generally, consumers do not register for VAT or file VAT returns simply because they purchase taxable goods/services. Businesses have substantial VAT compliance obligations.
VAT was introduced in the UAE on 1 January 2018. Standard VAT is set at a rate of 5%.
The UAE Government describes VAT as a consumption tax imposed through the production chain and the end customer ultimately pays.
VAT typically affects pricing strategies, sometimes resulting in higher prices. VAT can also affect cash flow, particularly when there is a timing gap between collecting VAT from customers and paying suppliers/settling VAT with the FTA.
Businesses collect VAT from customers and remit it to the government. Poor invoice and transaction classification can create problems with input VAT recovery. VAT therefore affects more than the final selling price since it also affects bookkeeping, working capital and tax reporting.
A VAT-registered business charges VAT on taxable supplies, collects it from its customers, accounts for eligible input VAT, and reports its net VAT position to the FTA.
However, some supplies are considered as:
Note
The mandatory AED 375,000 VAT registration threshold is not the same thing as the AED 375,000 Corporate Tax threshold:
Import duties, commonly referred to as customs duties are imposed on imported goods paid by the importer.
The standard customs duty rate for many goods is 5%, although rates vary depending on the type of goods.
Certain goods can attract higher customs duty rates. For example, UAE Government lists rates of 50% for alcohol and 100% for cigarettes.
Customs duty and import VAT are separate considerations. Founders importing goods should therefore avoid treating “5% customs duty” as the complete tax cost of importing.
The applicable customs classification, origin, value and exemptions can affect the amount payable.
Excise Tax targets specific goods considered harmful to health or the environment rather than applying broadly to ordinary consumption.
Currently, the government identifies excise goods including:
Tobacco and tobacco products, electronic smoking products/accessories and energy drinks are subject to a 100% excise rate under the relevant rules.
Note
From 1 January 2026, sweetened drinks are subject to the UAE’s Tiered-Volumetric Model for Excise Tax. The tax is determined based on the drink’s sugar and other sweetener content per 100 ml, rather than the previous flat percentage.
The current bands are:
Carbonated drinks are no longer a separate Excise Tax category from 2026; they are assessed under the sweetened-drinks regime where applicable
| Tax Type | What it applies to | Founder – level Example |
|---|---|---|
| VAT | Taxable goods and services | A UAE business sells AED 100,000 of standard-rated services → AED 5,000 VAT before considering other VAT adjustments |
| Excise Tax | Specific goods such as tobacco, electronic smoking devices and liquids used in such devices, energy drinks and certain beverages | A manufacturer or importer may have Excise Tax obligations in relation to applicable excise goods, depending on the activity and point at which the tax becomes due |
| Customs duty | Imported goods | Importer may owe customs duty before/at importation, depending on classification and applicable rate |
To further understand the difference between the two, it helps to classify it based on:
With a direct tax such as Corporate Tax, the company itself has the legal obligation to calculate and pay the tax.
With an indirect tax such as VAT, the business may have the legal responsibility to account for the tax, while the consumer generally bears the economic burden through the price paid.
Indirect taxes are therefore closely connected to consumption and spending, rather than the taxpayer’s overall profitability. The broader term consumption tax is often used to describe taxes imposed on spending or consumption.
| Key Characteristic | Direct Tax | Indirect Tax |
|---|---|---|
| Main UAE example | Corporate Tax | VAT |
| Tax base | Taxable income/profits | Taxable supplies/consumption |
| Who is primarily liable? | Taxable person/business | Business accounts for tax, but VAT is ultimately borne by consumer |
| Typical calculation | Taxable income × applicable CT rate | Output VAT less recoverable input VAT |
| Registration | CT registration applies to taxable persons | VAT registration depends on thresholds/rules |
| Key founder concerns | Profit, deductions, exemptions, tax schedule, calculating taxable income | Pricing, invoicing, input VAT, cash flow and filing |
| Main federal administrator | FTA | FTA |
A business can be both VAT-registered and subject to Corporate Tax. They are separate tax regimes with separate calculations and compliance obligations.
| Key Differences | VAT | Corporate Tax |
|---|---|---|
| Tax base | Taxable supplies and imports | Taxable income, rather than turnover |
| Standard rate | 5% Certain supplies may be zero-rated or exempt | 9% on taxable income exceeding AED 375,000 |
| Registration Threshold | Mandatory VAT registration generally applies when the value of taxable supplies and imports exceeds AED 375,000 over the previous 12 months or is expected to exceed that threshold in the next 30 days Voluntary registration is allowed at AED 187,500 | Corporate Tax registration requirements apply to taxable persons. AED 375,000 is a tax-rate threshold, not a general CT registration threshold. Businesses within scope of CT are generally required to register, even if they qualify for a 0% rate or Small Business Relief. Natural persons are subject to CT when total turnover exceeds AED 1 million within a calendar year. |
| How it works | Businesses generally collect VAT from customers and account for it to the FTA | Businesses calculate their taxable income and pay Corporate Tax on the amount subject to tax |
| Input / deductions | Eligible input VAT may be recovered against output VAT | Certain business expenses may be deductible when calculating taxable income |
| Starting point for tax management | Sales and purchases subject to VAT | Accounting profit, followed by the required Corporate Tax adjustments |
| Key records | Tax invoices, sales and purchase records, and VAT treatment of transactions | Financial statements, accounting records, deductible and non-deductible expenses, exempt income and tax adjustments |
| Other areas to consider | Output VAT, input VAT, proper tax invoices | Related-party transactions, transfer pricing, tax losses, exemptions and available tax elections or reliefs |
| Main practical impact | Pricing, VAT recovery and cash flow | Taxable profit, deductions, tax liability and financial reporting in tax returns |
| Effect on cash flow | Businesses collect VAT from customers but may need to fund VAT payments before receiving customer cash, depending on payment timing | Tax is generally paid based on the business’s taxable income and resulting Corporate Tax liability |
Example:
To fully understand obligations and tax liabilities within the Corporate Tax vs VAT regimes, read more here.
Knowing which tax applies is only the first step. UAE businesses also need to know when they have to register, which records to keep, and when returns and payments are due. The FTA uses a Tax Registration Number (TRN) to identify registered businesses, with separate registration requirements for VAT and Corporate Tax.
Note
Not sure whether you need a TIN or TRN? Our guide explains the difference and walks you through how to get a TIN in the UAE.
Most businesses that fall within the UAE Corporate Tax rules need to register with the FTA and obtain a Corporate Tax TRN. Free Zone companies are not automatically exempt from registration simply because they operate in a Free Zone.
For individuals, the rules are slightly different. A natural person conducting a business in the UAE generally comes within Corporate Tax registration requirements when their business turnover exceeds AED 1 million in a calendar year.
Businesses should also pay attention to registration deadlines.
Late Corporate Tax registration can result in an AED 10,000 administrative penalty. The FTA currently has a penalty-waiver initiative subject to specific conditions, including filing the first Tax Return or Annual Declaration within seven months of the end of the first Tax Period or Financial Year.
VAT registration depends on the value of a business’s taxable supplies, imports and, for voluntary registration, certain taxable expenses, subject to the applicable rules
Once registered, a business receives a VAT TRN and takes on ongoing compliance responsibilities. This includes charging VAT correctly, keeping the required records, filing VAT returns and settling the resulting VAT liability with the FTA. VAT returns and payments are generally due within 28 days after the end of the relevant tax period.
The Domestic Minimum Top-up Tax (DMTT) is a separate component of the UAE’s Pillar Two framework and is designed to apply a 15% minimum effective tax rate to in-scope multinational enterprise groups.
The relevant framework uses a €750 million consolidated revenue threshold for groups within its scope. In other words, this is not an additional 9% tax that every UAE business needs to calculate.
Smaller businesses should not assume that the DMTT creates a new compliance obligation simply because they are subject to UAE Corporate Tax.
UAE businesses that transact with Related Parties or Connected Persons need to follow the arm’s length principle, meaning the transaction should be priced as if it were between independent parties under comparable circumstances. This can apply to both domestic and cross-border transactions, including dealings between UAE mainland, Free Zone and overseas entities.
For founders, this means related-party transactions should be properly priced, recorded and supported. Depending on the business and its transactions, the FTA may require transfer pricing disclosures or supporting documentation, including a master file or local file in certain cases.
Non-compliance can create Corporate Tax risks if the FTA determines that transactions were not conducted at arm’s length.
Important
Transfer pricing is not a separate tax that you pay directly to the FTA.
Instead, it helps determine whether transactions between related parties have been priced appropriately when calculating taxable income for Corporate Tax purposes.
Corporate tax is the most common example of a direct tax.
It is imposed on the taxable income of businesses and other taxable persons
The standard rate is 9% on taxable income exceeding AED 375,000, subject to the applicable rules.
Direct tax: levied directly on the taxpayer based on taxable income/profits earned — e.g. UAE Corporate Tax
Indirect tax: associated with transactions/consumption and collected directly through businesses — e.g. VAT
Yes. The more common and relevant form of direct tax is Corporate Tax.
The UAE does not have a general personal income tax. Certain specialized taxation also exists, such as the 20% tax applicable under Dubai’s foreign-bank tax regime, subject to its specific rules.
VAT is an indirect consumption tax charged through the supply chain, with the economic burden generally intended to fall on the end consumer.
VAT: 5% standard rate.
Excise Tax: applies to specified goods such as tobacco, e-smoking products, energy drinks and certain beverages.
Customs duties: apply to imported goods according to the applicable customs classification and rate.
Thank you!
We've received your request and will get back to you shortly.
Loading...
 Thank you!
We've received your request and will get back to you shortly.



 Contact Us


