

Tax Loss Carry Forward UAE: FTA Schedule Rules 2026
The UAE corporate tax law allows businesses to carry forward tax losses to offset against…
Businesses typically receive two types of orders. One is where the delivery of goods or services is completed immediately. And others where the delivery is completed later.
Recording immediate delivery is simple. Debit cash and credit the revenue account. Accounting for the second type of order is not as straightforward. The gap between receiving cash and the delivery creates something called deferred revenue.
This article is all about how deferred revenue works. We will discuss the meaning and significance of deferred revenue, why it is a liability, how it is recorded, its impact on your Corporate Tax liability, how it differs from accrued revenue, and some common mistakes made when dealing with deferred revenue.
Deferred revenue is recorded as a liability when the business receives cash payment before the goods or services are delivered. Deferred revenue, unearned revenue, and deferred income are commonly used to describe amounts received or due before the related goods or services are provided.
Deferred revenue arises when there is a gap between cash receipts and revenue recognition.
Examples of deferred revenue would be prepaid software or service subscriptions.
For a subscription service, the amount received is generally recorded as deferred revenue and recognized as actual revenue as the related performance obligations are satisfied. This is because IFRS 15, which is based on the revenue recognition principle, requires revenue to be recognized when or as the relevant performance obligation is satisfied.
Since the cash received by the business creates an obligation to deliver goods or services, or provide a refund, we call deferred revenue a liability. Deferred revenue is generally presented as a current liability when the related performance obligation is expected to be satisfied within the entity’s normal operating cycle or within 12 months, as applicable. Amounts expected to be settled beyond that period may be presented as non-current, subject to the applicable accounting requirements.
With every shipment or service delivery, the liability decreases, and revenue is recognized.
Thus, deferred revenue enters your books on the balance sheet and makes its way to the income statement, increasing your accounting profits that add to your equity.
Normally, when you make a sale, goods or services are going out, and cash comes in. But in the case of deferred revenue, cash still comes in, but no goods or services are going out. This gap is filled by deferred revenue. Here’s how a deferred revenue journal entry will look:
| Particulars | Debit | Credit |
|---|---|---|
| Cash Account | AED 4,000 | |
| Deferred Revenue Account | AED 4,000 |
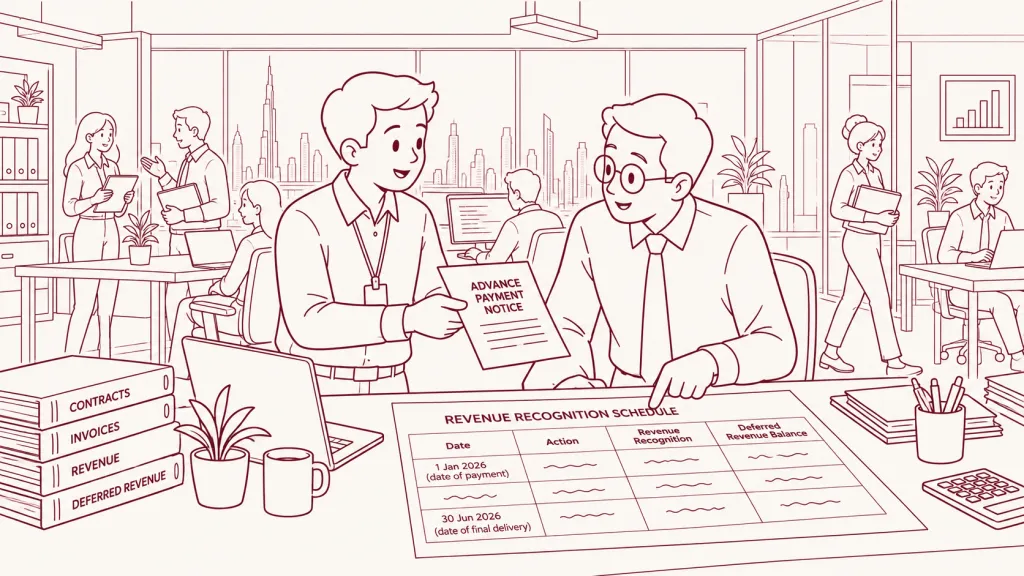
Now, let us see how deferred revenue is recorded and gradually reduced by recognizing revenue. Suppose a cafe chain places an order for a fixed monthly shipment of coffee beans for one year and pays AED 120,000 upfront on 1 January. Then, on the 15th of every month, you deliver the coffee beans.
DEFERRED REVENUE: JOURNAL ENTRIES
| Date | Particulars | Debit | Credit |
|---|---|---|---|
| 01.01.2026 | Bank Account | AED 120,000 | |
| Deferred Revenue Account | AED 120,000 | ||
| (AED 120,000 received upfront for the one-year supply agreement) | |||
| 15.01.2026 | Deferred Revenue Account | AED 10,000 | |
| Revenue Account | AED 10,000 | ||
| (January delivery of coffee beans completed) | |||
| 15.02.2026 | Deferred Revenue Account | AED 10,000 | |
| Revenue Account | AED 10,000 | ||
| (February delivery of coffee beans completed) | |||
| 15.03.2026 | Deferred Revenue Account | AED 10,000 | |
| Revenue Account | AED 10,000 | ||
| (March delivery of coffee beans completed) | |||
| 15.04.2026 | Deferred Revenue Account | AED 10,000 | |
| Revenue Account | AED 10,000 | ||
| (April delivery of coffee beans completed) | |||
| 15.05.2026 | Deferred Revenue Account | AED 10,000 | |
| Revenue Account | AED 10,000 | ||
| (May delivery of coffee beans completed) | |||
| 15.06.2026 | Deferred Revenue Account | AED 10,000 | |
| Revenue Account | AED 10,000 | ||
| (June delivery of coffee beans completed) | |||
| 15.07.2026 | Deferred Revenue Account | AED 10,000 | |
| Revenue Account | AED 10,000 | ||
| (July delivery of coffee beans completed) | |||
| 15.08.2026 | Deferred Revenue Account | AED 10,000 | |
| Revenue Account | AED 10,000 | ||
| (August delivery of coffee beans completed) | |||
| 15.09.2026 | Deferred Revenue Account | AED 10,000 | |
| Revenue Account | AED 10,000 | ||
| (September delivery of coffee beans completed) | |||
| 15.10.2026 | Deferred Revenue Account | AED 10,000 | |
| Revenue Account | AED 10,000 | ||
| (October delivery of coffee beans completed) | |||
| 15.11.2026 | Deferred Revenue Account | AED 10,000 | |
| Revenue Account | AED 10,000 | ||
| (November delivery of coffee beans completed) | |||
| 15.12.2026 | Deferred Revenue Account | AED 10,000 | |
| Revenue Account | AED 10,000 | ||
| (December delivery of coffee beans completed) |
Over 2026, your deferred revenue with respect to this order will decrease in the following manner.
| Date | Action | Revenue recognition | Deferred revenue balance |
|---|---|---|---|
| 01.01.2026 | Order received | AED 0 | AED 120,000 |
| 15.01.2026 | January delivery completed | AED 10,000 | AED 110,000 |
| 15.02.2026 | February delivery completed | AED 10,000 | AED 100,000 |
| 15.03.2026 | March delivery completed | AED 10,000 | AED 90,000 |
| 15.04.2026 | April delivery completed | AED 10,000 | AED 80,000 |
| 15.05.2026 | May delivery completed | AED 10,000 | AED 70,000 |
| 15.06.2026 | June delivery completed | AED 10,000 | AED 60,000 |
| 15.07.2026 | July delivery completed | AED 10,000 | AED 50,000 |
| 15.08.2026 | August delivery completed | AED 10,000 | AED 40,000 |
| 15.09.2026 | September delivery completed | AED 10,000 | AED 30,000 |
| 15.10.2026 | October delivery completed | AED 10,000 | AED 20,000 |
| 15.11.2026 | November delivery completed | AED 10,000 | AED 10,000 |
| 15.12.2026 | December delivery completed | AED 10,000 | AED 0 |
Unless you have just started out, a business will rarely have just one client. That means multiple deferred revenue balances that must be tracked to calculate your accounting profits and track your financial performance. A well-organized chart of accounts enables you to classify and track deferred revenue in greater detail. In a previous article, we discussed how businesses should set up their chart of accounts to effectively track financial performance.
In the UAE, Corporate Tax generally starts with the accounting income reported in the financial statements. This accounting income is then adjusted as required under the Corporate Tax Law to determine taxable income. As a result, the timing of revenue recognition can affect taxable income.
So, you can have a low Corporate Tax liability while having high cash inflows because your business is yet to deliver on its orders.
The opposite may happen in a later tax period. If more revenue is recognized in that period than the cash collected from customers, the business may have a Corporate Tax liability even though its cash inflows are comparatively lower.
Businesses whose revenue does not exceed AED 3 million can elect to maintain books on a cash basis, subject to the applicable requirements. Under the cash basis, income is generally recognized when cash is received and expenditure when cash is paid. For these businesses, there will not be a gap between cash flows and revenue recognition. However, these businesses are the exception and not the norm.
Does your business fall within the AED 3 million threshold? Learn the pros and cons of cash basis accounting and how it compares with accrual basis accounting in our guide to cash and accrual basis accounting.
Because of deferred revenue, maintaining enough cash reserves for Corporate Tax liabilities becomes an important consideration. With businesses that have significant annual contracts, there’s a chance of not being able to pay Corporate Tax on time.
One way to avoid late payment of Corporate Tax for this reason would be to prepare monthly financial statements. This helps you keep track of the revenue recognized in each month and the Corporate Tax liability created. Unless otherwise required, most businesses only prepare annual financial statements. However, as part of our accounting and tax package, Skrooge provides monthly financial statements so that business owners can make informed decisions about tax planning and other business objectives. Learn more about Skrooge’s accounting and tax package.
Deferred revenue and accrued revenue are mirror images of each other. Deferred revenue arises when consideration is received or due before the related goods or services are provided. Accrued revenue generally arises when revenue has been earned before it is billed or collected. While deferred revenue is a liability, accrued revenue is an asset. Let us dive deeper into the differences between deferred revenue and accrued revenue.
| Deferred revenue | Accrued revenue | |
|---|---|---|
| Origin | Receiving cash before delivering goods or services | Revenue earned before it is billed or collected |
| What does it represent? | Obligation to provide goods, services, or refunds | Right to receive cash |
| Where does it appear in financial statements? | Liability section of the balance sheet | Asset section of the balance sheet |
| How does it complicate Corporate Tax? | Gap between receipt of cash and revenue recognition means businesses must actively choose between maintaining enough cash for Corporate Tax obligations or deploying cash for business operations or expansion | Revenue is recognized early, which means that Corporate Tax is due before cash is received |
Here are some common mistakes businesses make when it comes to deferred revenue:
|
Mistake |
What does this lead to? |
|---|---|
|
Recognizing the full invoice on issue |
Creates an inaccurate picture of the company’s financial performance Obligation to pay Corporate Tax kicks in sooner than it normally would |
|
No schedule to unwind the balance |
Calculations relating to deferred revenue must be performed from scratch every time a delivery is made instead of simply following a revenue recognition schedule made in advance |
|
VAT accounted for at the wrong point |
Late VAT recognition, payment and recovery, which may lead to penalties Note: Typically, VAT must be charged on the earliest of:
|
|
Lack of Corporate Tax provisions |
Cash crunches or late Corporate Tax payments which may lead to penalties |
The deferred revenue mechanism leads to more accurate financial reporting. It allows you to distinguish between cash-flow trends and revenue-recognition trends. One key drawback, however, is that keeping up with Corporate Tax liabilities will require better cash flow management.
Since you have 9 months from the end of your tax period to pay Corporate Tax, you may want to deploy some of the cash received as deferred revenue to expand your business or for day-to-day operations. However, that requires careful planning based on clear visibility into Corporate Tax obligations.
Let’s say you use cash received in advance from customers to acquire new clients, open a new branch, or fund some other business expansion.
Without monthly financial statements, in the Corporate Tax filing season, you might be left scrambling to figure out the tax liability and arrange for cash through whatever means possible.
As part of our Accounting and Tax package, you get monthly financial statements, filing support for VAT and Corporate Tax, and much more at prices within the reach of UAE SMEs.
Learn more about what’s included in this package and how it’s priced!
In simple terms, deferred revenue is the value of goods or services for which you have already received money but haven’t yet delivered.
Deferred revenue is a liability because it represents an obligation to deliver goods or services, or to provide a refund.
When cash is received and deferred revenue is created, the deferred revenue account will be credited. When goods or services are delivered, the deferred revenue account is debited.
Deferred revenue is a liability created when you receive money for goods or services you are expected to deliver in the future. Accrued income is an asset arising when revenue has been earned but has not yet been billed or collected.
UAE Corporate Tax generally starts with accounting net profit or loss, which is then adjusted under the Corporate Tax Law to determine Taxable Income. The accrual accounting principle is the default for accounting profit calculation.
Thank you!
We've received your request and will get back to you shortly.
Loading...
 Thank you!
We've received your request and will get back to you shortly.






 Contact Us


